
Indian Income Tax Basics 2027: Complete Guide for Students & Taxpayers
By Sudip Sengupta | Tfin Career
Indian Taxation Study Material 2027 — Module 1, Chapter 1
Last Updated: September 23, 2026
Introduction
This Indian taxation study material series is designed to build your understanding step by step, from basic tax concepts to income classification, computation and return filing.
Indian income tax becomes much easier to understand when the basic concepts are learned in the right order.
Before studying residential status, exempt income, deductions, tax rates, TDS, return filing or detailed income computation, a learner needs to understand the foundation: What is income tax? What is taxable income? How is income classified? Who administers income tax? What is a Tax Year?
This chapter provides that foundation.
It is designed for students preparing for taxation examinations, learners who want to understand Indian taxation from the beginning, and taxpayers who want a clear introduction to the Indian income-tax system.
The objective is not to memorize isolated rules. Instead, the aim is to understand how the pieces of the tax system fit together.
Learn the concept first. Apply the tax rule second.
Table of Contents
2027 Tax-Law Update
The Indian tax framework has entered an important transition.
For Tax Year 2026–27 and subsequent Tax Years, the Income-tax Act, 2025 applies under the new framework. For earlier periods, the Income-tax Act, 1961 continues to apply as applicable. The new Act uses the term “Tax Year” instead of “Previous Year” and does not use the earlier “Assessment Year” concept for the new framework. The Income Tax Department explains that Tax Year 2026–27 refers to Financial Year 2026–27.
This means that students preparing for 2027 examinations or tax-related work should pay particular attention to the applicable tax year.
For example:
Financial Year 2026–27 → Tax Year 2026–27
The older framework continues to matter for earlier periods. For example, income earned during FY 2025–26 is dealt with under the Income-tax Act, 1961 and is filed for AY 2026–27. The Income Tax Department has specifically clarified this transition.
Students who want an additional foundation can review our fundamentals of income tax law in India before moving into the detailed chapters.
Study Rule
Whenever you learn a tax provision, ask:
“Which tax year does this rule apply to?”
That simple question can prevent many mistakes.
Module 1 — Foundations of Indian Income Tax Basics
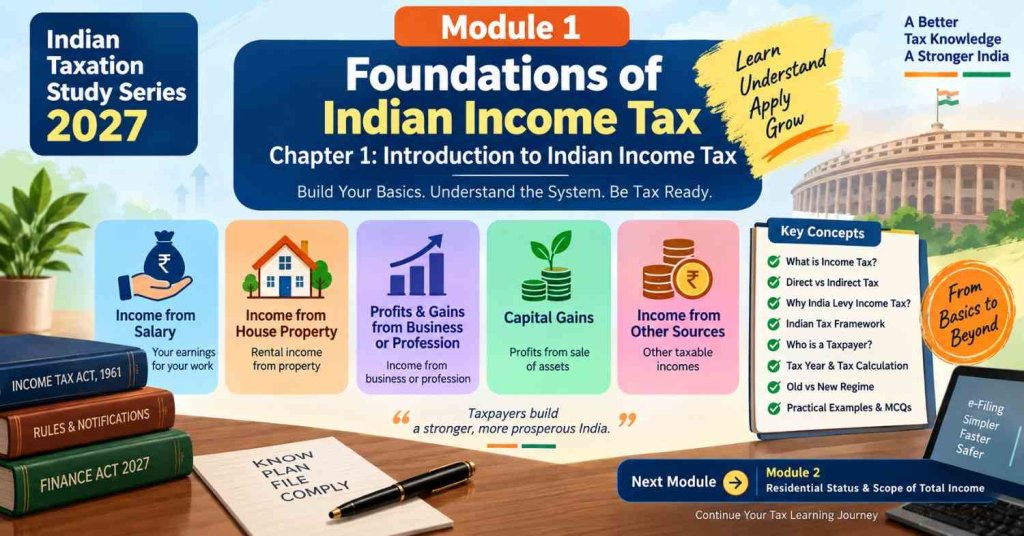
Module 1 establishes the basic knowledge required before moving into detailed income computation and tax compliance.
Module 1 Chapters
- Chapter 1 — Introduction to Indian Income Tax
- Chapter 2 — Important Income Tax Terminology
- Chapter 3 — Residential Status
- Chapter 4 — Scope of Total Income
- Chapter 5 — Exempt Income
- Chapter 6 — Tax Rates and Tax Regimes
Study Path
Complete Chapters 1–6 in sequence.
After completing Module 1, you will be ready to move into Module 2 — Detailed Study of the Five Heads of Income.
Chapter 1 — Introduction to Indian Income Tax
Learning Objectives
After completing this chapter, you should be able to:
- Explain the basic meaning of income tax.
- Understand the difference between direct and indirect taxes.
- Describe the basic structure of Indian income taxation.
- Identify the five major heads of income.
- Understand the role of the Income Tax Department and CBDT.
- Explain the difference between gross income and taxable income.
- Understand why the applicable tax year matters.
- Describe the basic stages of tax computation.
- Understand the relationship between income, tax liability and compliance.
- Prepare for introductory taxation examination questions.
1. What Is Income Tax?
Income tax is a direct tax imposed on taxable income according to the income-tax law applicable to the relevant tax year.
The basic idea can be represented simply:
Income earned
      ↓
Income classified
      ↓
Taxable income determined
      ↓
Tax calculated
      ↓
Tax liability determined
      ↓
Tax paid / compliance completed
This looks simple, but each stage can involve detailed rules.
A person may receive money from several sources, including:
- Salary
- Business or professional activities
- House property
- Capital gains
- Interest and other sources
The tax law determines how the relevant income is treated.
It may determine:
- Whether an amount is income.
- Whether the income is taxable.
- Whether an exemption or exclusion applies.
- Whether a deduction is available.
- Which rate applies.
- Whether special-rate provisions apply.
- The final tax liability.
- The applicable compliance requirements.
Therefore, receiving income and having taxable income are not necessarily the same thing.
2. Direct Tax vs Indirect Tax
One of the first concepts a taxation student should understand is the difference between direct taxation and indirect taxation.
| Basis | Direct Tax | Indirect Tax |
|---|---|---|
| Basic idea | Tax imposed directly on the taxpayer | Tax generally collected through transactions or supplies |
| Common example | Income tax | GST |
| Main relationship | Connected directly with the taxpayer’s liability | Generally connected with supply or consumption |
| Economic burden | Generally borne by the person on whom the liability is imposed | May be passed through the supply chain |
| Main area | Income and certain gains | Goods and services |
Easy Memory Rule
Income Tax = Direct Tax
GST = Indirect Tax
This distinction is particularly useful when answering introductory examination questions.
3. Why Does India Levy Income Tax?
Income tax forms an important part of government revenue.
Tax revenue helps support government expenditure and public services, including areas such as:
- Infrastructure
- Public administration
- Education
- Healthcare
- Public services
- Social programmes
- National development
For a student, however, it is important to understand that taxation is not simply about collecting money.
A tax system establishes a legal framework for determining:
- who is liable,
- what income is taxable,
- how taxable income is calculated,
- what rates apply,
- what deductions or exemptions are available,
- and how taxpayers meet their compliance obligations.
In other words:
Taxation connects income, law, computation and compliance.
4. Indian Income Tax Basics Framework
The Indian income-tax system operates through legislation, rules, notifications, administrative procedures and the tax administration system.
A simplified learning model is:
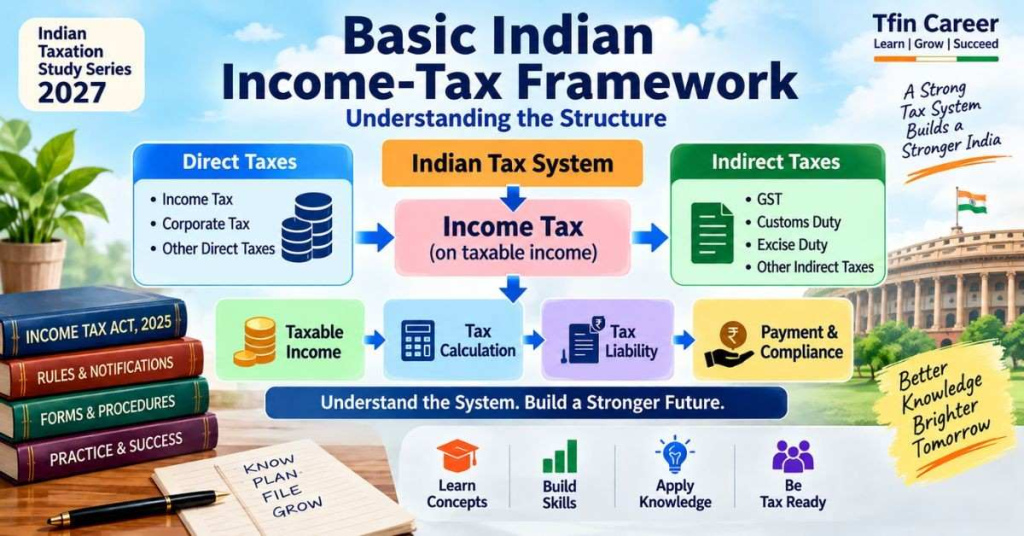
This is a learning diagram, not a complete description of every Indian tax.
The exact law, terminology, rates, procedures and forms must always be checked for the relevant tax year.
5. Income-Tax Law: A Student’s Basic Map
When beginning taxation studies, it is useful to think of income tax as a connected system rather than a collection of unrelated chapters.
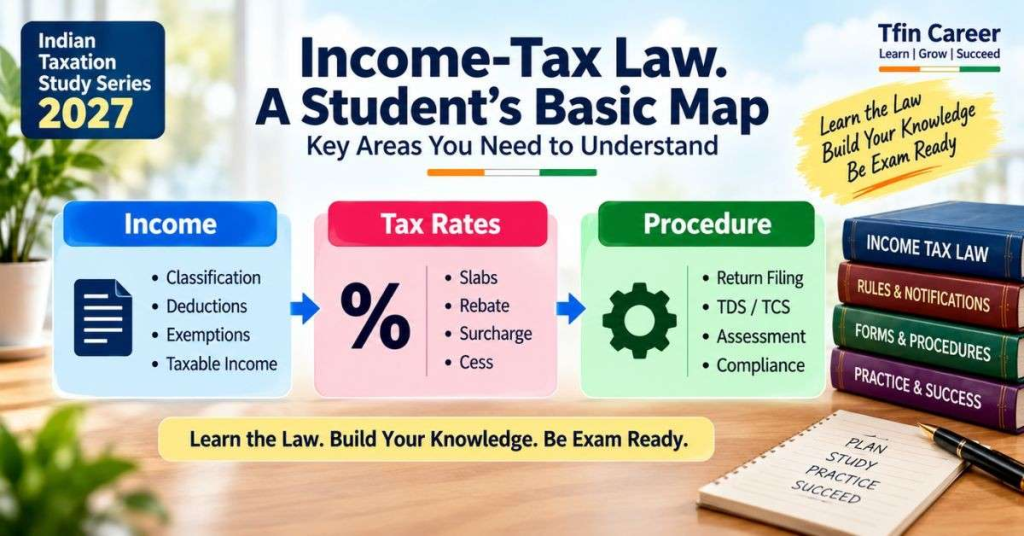
This model helps explain why a tax calculation cannot normally be completed simply by taking the amount of money received and multiplying it by one rate.
6. Gross Income Is Not Automatically Taxable Income
This is one of the most important concepts for beginners.
Suppose a person receives:
- Salary: ₹8,00,000
- Interest: ₹50,000
The total receipts considered in this simplified example are:
₹8,50,000
But it would be incorrect to automatically conclude that ₹8,50,000 is the person’s final taxable income.
Depending on the applicable provisions, the calculation may involve:
- Exempt amounts
- Allowances
- Deductions
- Loss adjustments
- Special tax treatment
- Rebate provisions
- Other statutory adjustments
The simplified concept is:
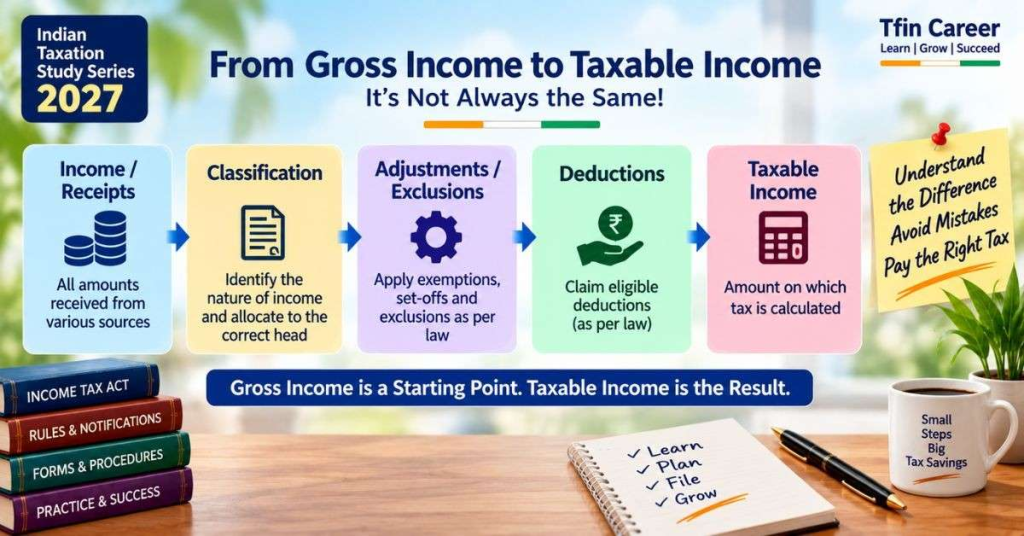
Remember
Gross receipts and final taxable income are not automatically the same.
7. The Five Major Heads of Income
Classification of income is one of the foundations of Indian income-tax study.
For study purposes, income is broadly organized under five major heads:
- Income from Salary
- Income from House Property
- Profits and Gains from Business or Profession
- Capital Gains
- Income from Other Sources
Let’s understand the basic idea behind each.
7.1 Income from Salary
This head deals with income arising from an employer-employee relationship, subject to the applicable provisions.
Examples can include:
- Salary
- Bonus
- Commission
- Certain allowances
- Perquisites
- Certain pension income
Detailed treatment of salary will be covered later in the series.
7.2 Income from House Property
This head generally deals with taxable income arising from ownership of house property under the applicable provisions.
The detailed computation will depend on the nature of the property and the applicable law.
Residential status, ownership, property use, deductions and other rules can become important when this head is studied in detail.
7.3 Profits and Gains from Business or Profession
This head covers income arising from business or professional activities, subject to the applicable tax provisions.
Examples include:
- Business profits
- Professional receipts
- Certain freelance income
- Income from professional activities
Detailed computation requires consideration of applicable business and professional provisions.
7.4 Capital Gains
Capital gains generally arise from the transfer of a capital asset when the applicable conditions are satisfied.
Examples of assets may include:
- Land
- Buildings
- Shares
- Securities
- Other capital assets
Capital gains involve their own classification and computation rules and will be studied separately in the series.
7.5 Income from Other Sources
This is generally a residual head for taxable income that does not fall under the other specified heads, subject to the applicable provisions.
Examples may include certain types of:
- Interest income
- Dividend income
- Other taxable receipts
The exact tax treatment depends on the relevant provision and nature of income.
Five Heads — Quick Diagram
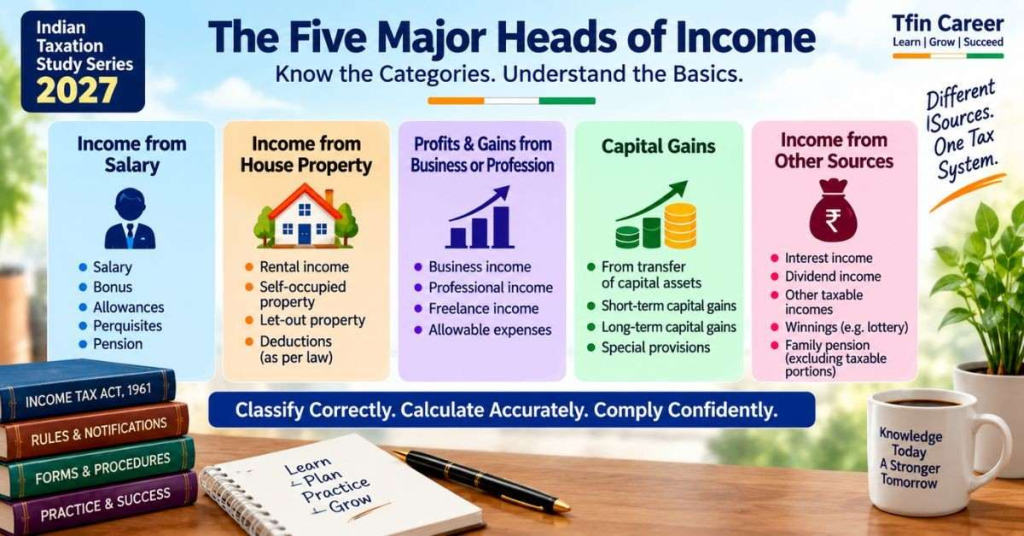
Exam Memory Trick
S – H – B – C – O
Salary → House Property → Business/Profession → Capital Gains → Other Sources
8. Who Is a Taxpayer?
In everyday conversation, the word taxpayer is commonly used for someone who has a tax obligation.
Tax law, however, uses specific statutory terminology.
One important term is “person.”
Depending on the applicable law, the concept of person can cover categories such as:
- Individual
- Hindu Undivided Family (HUF)
- Company
- Firm
- Association of Persons (AOP)
- Body of Individuals (BOI)
- Local authority
- Artificial juridical person
Students should distinguish everyday language from statutory terminology.
This distinction becomes increasingly important when studying the definition of person, assessee, taxpayer, and related terms in Chapter 2.
9. Who Administers Income Tax in India?
The Income Tax Department is responsible for administering India’s direct-tax system.
The Central Board of Direct Taxes (CBDT) is the statutory board dealing with matters relating to direct taxes and functions under the Department of Revenue, Ministry of Finance.
For a beginner, the relationship can be remembered as:
Ministry of Finance
        ↓
Department of Revenue
        ↓
       CBDT
        ↓
Income Tax Department
        ↓
Tax Administration
The tax administration system includes functions such as:
- Taxpayer services
- Tax collection
- Return processing
- Compliance activities
- Administration of tax provisions
- Investigation and related functions
Exam Tip
Remember:
CBDT → Direct Taxes
10. Income Tax and the Tax Year
This is particularly important for students studying Indian taxation in 2027.
Under the Income-tax Act, 2025, the term “Tax Year” replaces the previous “Previous Year” terminology for the new framework, and the earlier “Assessment Year” concept is discontinued under the new Act. The Income Tax Department states that the Tax Year concept applies from 1 April 2026, beginning with income for FY 2026–27.
Therefore:
Financial Year 2026–27
          ↓
Tax Year 2026–27
The new terminology creates a more direct connection between the year in which income is earned and the Tax Year reference.
Important Transition Point
Do not assume that all earlier tax records suddenly use the new terminology.
For income relating to FY 2025–26, the applicable return remains under the Income-tax Act, 1961 and is filed for AY 2026–27. The Income Tax Department specifically explains this transition.
Study Rule
Before applying a tax provision:
Identify the relevant period first.
Then identify:
- The applicable Act.
- The applicable tax year or assessment year.
- The relevant provision.
- The applicable rate or computation rule.
- The filing or compliance requirement.
11. How Income Tax Works — A Simple Model
A beginner can visualize the tax process as follows:
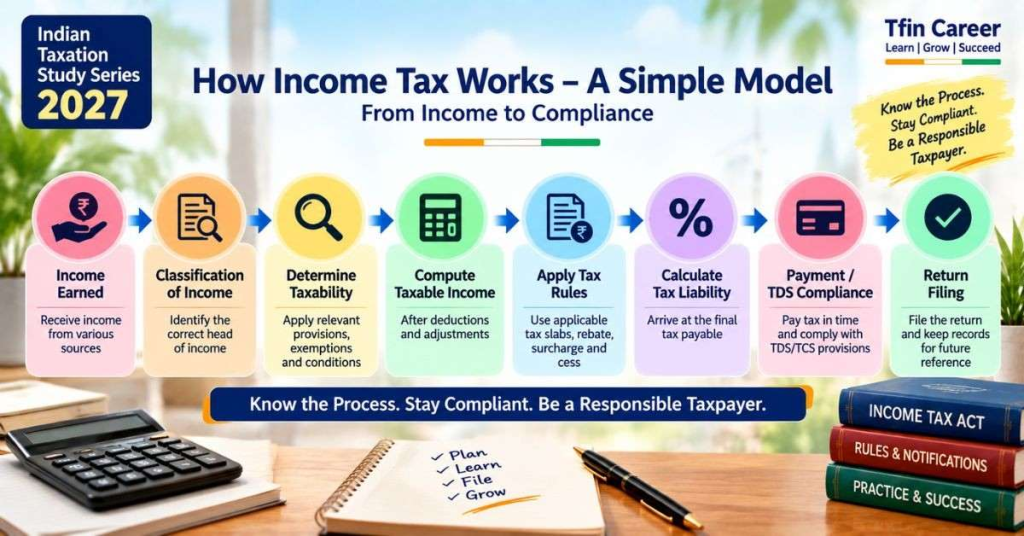
This is a simplified educational model.
Actual calculations can be more complicated because different types of income can be subject to different provisions.
12. Tax Calculation — Basic Concept
A simplified tax calculation can be represented as:
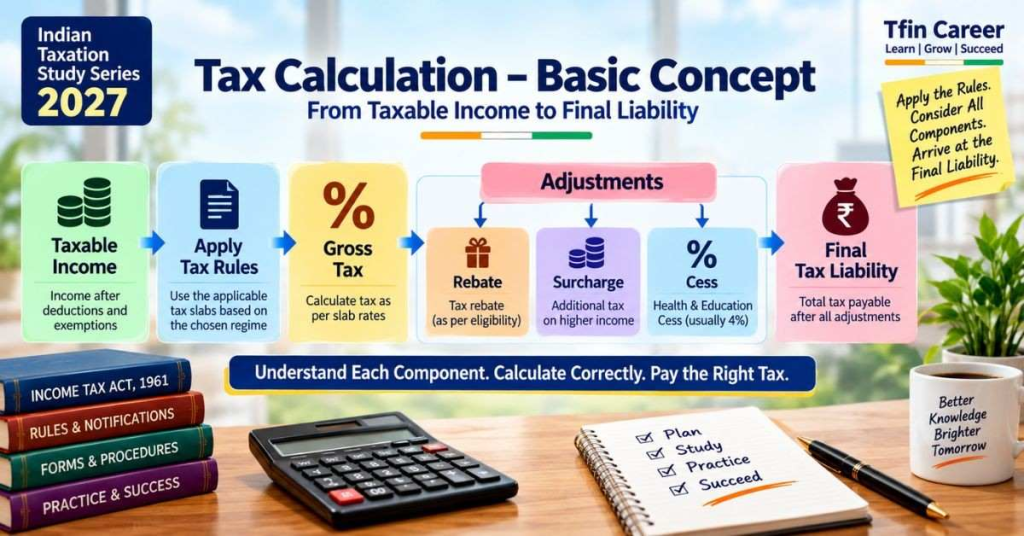
The actual calculation depends on:
- Taxpayer category
- Applicable tax year
- Nature of income
- Applicable tax regime
- Tax rates
- Deductions
- Exemptions
- Rebate
- Surcharge
- Cess
- Special-rate provisions
- Other applicable rules
Therefore, students should never memorize a simplified diagram as though it were a complete statutory tax computation.
13. Understanding Tax Regimes
Tax-regime choices are an important part of individual taxation.
A common mistake is to compare regimes only by looking at their headline tax rates.
A better approach is:
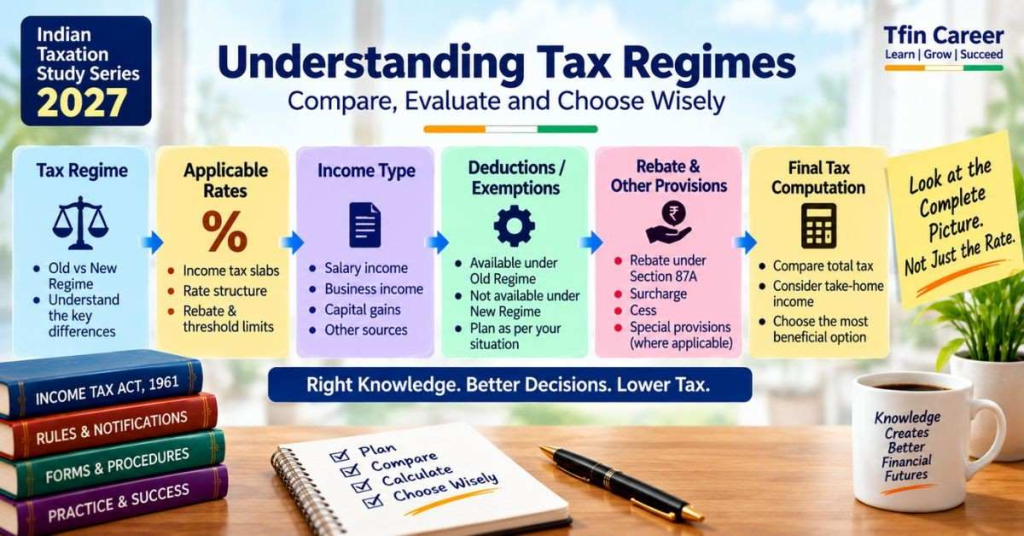
When studying a tax regime, consider:
- Applicable income
- Type of income
- Eligible deductions
- Available exemptions
- Rebate
- Surcharge
- Cess
- Special-rate income
- Applicable tax year
The Income Tax Department’s current tax-calculation tools distinguish between the Income-tax Act, 2025 for Tax Year 2026–27 and the Income-tax Act, 1961 for earlier assessment years.
Key Lesson
Never compare tax regimes using one number alone.
The complete calculation matters.
14. Practical Example — Understanding Taxable Income
Example 1: Basic Income Classification
Suppose Rahul receives:
| Income Source | Amount |
|---|---|
| Salary | ₹7,00,000 |
| Bank interest | ₹30,000 |
| Other taxable income | ₹20,000 |
| Total receipts in this simplified example | ₹7,50,000 |
At first glance, Rahul has ₹7,50,000 of receipts.
But that does not automatically establish his final taxable income.
The tax computation must consider the applicable:
- Income-tax provisions
- Income classification
- Exemptions
- Deductions
- Tax regime
- Tax rates
- Rebate
- Cess
- Other applicable adjustments
Lesson
Income received ≠ automatically final taxable income.
This distinction becomes increasingly important when you begin studying actual tax computations.
15. Practical Example — Following the Tax Journey
Consider another simplified example.
Priya receives salary and interest income during a tax year.
Her first task is not to calculate tax immediately.
She should first identify:
This approach is more reliable than beginning with a tax slab.
16. Exam-Oriented Questions & Answers
Q1. What is income tax?
Answer:
Income tax is a direct tax imposed on taxable income according to the income-tax law applicable to the relevant tax year.
Q2. Is income tax a direct tax?
Answer:
Yes. Income tax is generally classified as a direct tax because the liability is imposed directly on the taxpayer under the applicable law.
Q3. What are the five major heads of income?
Answer:
- Income from Salary
- Income from House Property
- Profits and Gains from Business or Profession
- Capital Gains
- Income from Other Sources
Q4. What does CBDT stand for?
Answer:
CBDT stands for Central Board of Direct Taxes. It is the statutory board dealing with matters relating to direct taxes under the Department of Revenue, Ministry of Finance.
Q5. Is gross income always equal to taxable income?
Answer:
No. Gross income may require statutory adjustments, exclusions, deductions and other applicable provisions before taxable income is determined.
Q6. Why is the applicable tax year important?
Answer:
Tax provisions, terminology, rates, procedures and filing requirements can vary according to the relevant period. Therefore, the applicable tax year must be identified before applying a tax rule.
Q7. What is the Tax Year under the Income-tax Act, 2025?
Answer:
Under the new framework, a Tax Year is a twelve-month financial year beginning on 1 April. Tax Year 2026–27 refers to Financial Year 2026–27.
17. MCQ Practice — Indian Income Tax Basics 2027
Question 1
Income tax is generally classified as:
A. Indirect tax
B. Direct tax
C. Consumption tax
D. Customs duty
Correct Answer: B — Direct tax
Question 2
Which of the following is a major head of income?
A. Salary
B. GST
C. Customs duty
D. Stamp duty
Correct Answer: A — Salary
Question 3
Which of the following is one of the five major heads of income?
A. Capital Gains
B. GST
C. Customs duty
D. Registration fee
Correct Answer: A — Capital Gains
Question 4
CBDT is primarily associated with:
A. Direct taxes
B. Railway administration
C. Monetary policy
D. Foreign trade
Correct Answer: A — Direct taxes
Question 5
Which sequence best represents the basic tax-computation process?
A. Tax → Income → Return
B. Income → Classification → Taxable Income → Tax Calculation
C. Return → Income → Tax
D. Deduction → Receipt → Income
Correct Answer: B
Question 6
Which is one of the five major heads of income?
A. House Property
B. GST
C. Import Duty
D. Registration Fee
Correct Answer: A — House Property
Question 7
Salary income is generally studied under:
A. Capital Gains
B. Income from Other Sources
C. Income from Salary
D. House Property
Correct Answer: C — Income from Salary
Question 8
Income arising from the transfer of a capital asset may result in:
A. Salary income
B. Capital Gains
C. House Property income
D. GST
Correct Answer: B — Capital Gains
Question 9
Which statement is correct?
A. Gross receipts always equal taxable income.
B. Taxable income may require statutory adjustments.
C. All receipts are automatically exempt.
D. All income is taxed at one rate.
Correct Answer: B — Taxable income may require statutory adjustments.
Question 10
Before applying an income-tax rule, a student should first identify:
A. Social-media trends
B. Applicable tax year
C. Bank balance
D. GST registration
Correct Answer: B — Applicable tax year
18. Quick Check
Try answering these questions without looking back.
- What type of tax is income tax?
- What are the five major heads of income?
- What does CBDT stand for?
- Is gross income necessarily the same as taxable income?
- Why is the applicable tax year important?
- What is the difference between direct and indirect taxation?
- Give two examples of income sources.
- What is the basic purpose of tax computation?
- What is Tax Year 2026–27?
- Which Act applies to income covered by Tax Year 2026–27?
Answers
- Direct tax.
- Salary, House Property, Business/Profession, Capital Gains and Other Sources.
- Central Board of Direct Taxes.
- No.
- Because the applicable provisions and terminology depend on the relevant period.
- Direct tax is imposed directly on the taxpayer; indirect taxation generally operates through transactions or supplies.
- Salary and interest are examples.
- To determine tax liability under the applicable law.
- It refers to Financial Year 2026–27 under the new framework.
- The Income-tax Act, 2025.
19. Exam Tip
Remember this sequence:
Income → Classification → Taxability → Taxable Income → Tax Calculation → Tax Liability → Compliance
And remember the five major heads:
S – H – B – C – O
Salary → House Property → Business/Profession → Capital Gains → Other Sources
One-Line Memory Rule
Classify first. Calculate second.
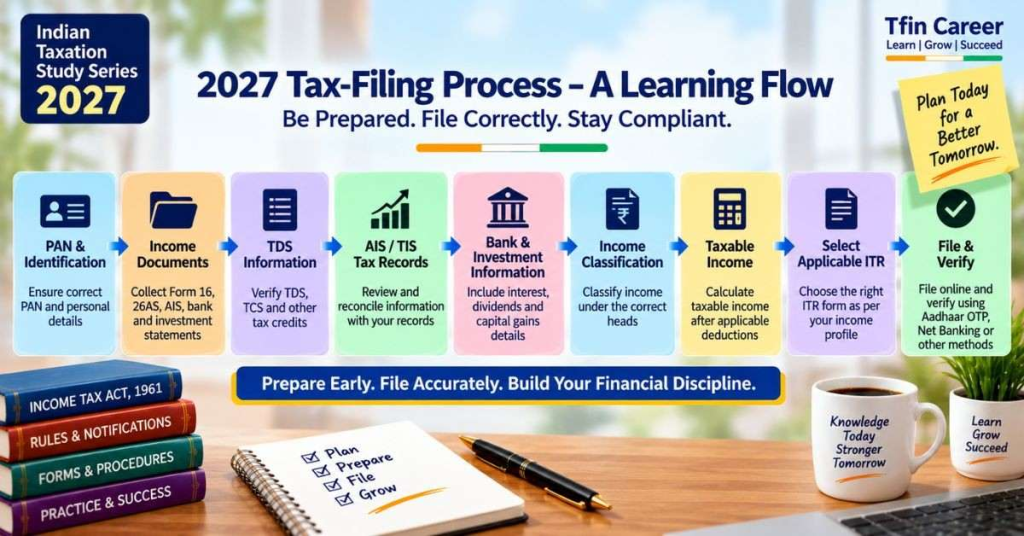
20. 2027 Tax-Filing Tip
When preparing for an actual return, do not begin by opening the ITR form without first understanding your income information.
A practical learning sequence is:
PAN / Identification
        ↓
Salary / Income Documents
        ↓
TDS Information
        ↓
AIS / TIS / Applicable Tax Records
        ↓
Bank & Investment Information
        ↓
Income Classification
        ↓
Taxable Income Computation
        ↓
Tax Liability
        ↓
Applicable Return
        ↓
Filing & Verification
For Tax Year 2026–27 and later periods, taxpayers must use the framework applicable under the Income-tax Act, 2025. The Income Tax Department has also begun rolling out forms and related services under the new Act.
The detailed return-filing process will be covered in the later modules of this series.
21. Chapter Summary
You have now established the foundation for studying Indian income taxation.
Remember These 10 Points
| No. | Key Point |
|---|---|
| 1 | Income tax is generally a direct tax. |
| 2 | Taxability depends on the applicable law. |
| 3 | Income must be properly classified. |
| 4 | There are five major heads of income. |
| 5 | Gross receipts are not automatically final taxable income. |
| 6 | CBDT deals with matters relating to direct taxes. |
| 7 | The applicable tax year must be identified. |
| 8 | Tax computation determines the taxpayer’s liability. |
| 9 | The Income-tax Act, 2025 applies to Tax Year 2026–27 onwards under the new framework. |
| 10 | Tax study should move from concepts to computation and then to compliance. |
22. Frequently Asked Questions
What is income tax in India?
Income tax is a direct tax imposed on taxable income under the income-tax law applicable to the relevant period.
What are the five heads of income?
The five major heads are Income from Salary, Income from House Property, Profits and Gains from Business or Profession, Capital Gains and Income from Other Sources.
Is gross income the same as taxable income?
Not necessarily. Taxable income may require adjustments, exclusions, deductions and other statutory treatment.
What is CBDT?
CBDT means Central Board of Direct Taxes. It is the statutory board dealing with matters relating to direct taxes under the Department of Revenue, Ministry of Finance.
What is Tax Year 2026–27?
Tax Year 2026–27 refers to Financial Year 2026–27 under the Income-tax Act, 2025.
Does Assessment Year continue under the Income-tax Act, 2025?
The Income Tax Department states that the Assessment Year concept is not used under the Income-tax Act, 2025; the new framework uses Tax Year terminology. Earlier periods continue to be governed by the Income-tax Act, 1961 as applicable.
Why should students identify the tax year first?
Because the applicable law, terminology, rates, procedures and forms can depend on the relevant period.
23. Official Indian Income-Tax Resources
For current tax information, students should give priority to official government sources.
Income Tax Department
Income Tax Department — Official Portal
Income-tax Act, 2025
Income Tax Department — Income-tax Act, 2025
New Act — Objective and Scope
Income Tax Department — Objective and Scope of the New Act
Tax Year and General Questions
Income Tax Department — General Questions
Important Study Reminder
Tax laws, rules, rates, forms, notifications and procedures can change.
Always verify a tax rule against the law and official guidance applicable to the relevant tax year.
24. Educational Disclaimer
This chapter is provided for educational and study purposes.
It is intended to help students, learners and taxpayers understand fundamental Indian income-tax concepts. It should not be treated as personalized legal, tax or financial advice.
Indian tax laws, rates, exemptions, deductions, forms, procedures and compliance requirements may change.
Before making a tax decision or filing a return, verify the rules applicable to the relevant tax year using the current legislation, notifications, rules and official Income Tax Department guidance.
25. About the Author
Sudip Sengupta
Author & Taxation Education Content Creator — Tfin Career
Sudip Sengupta develops structured educational content covering taxation, finance and practical financial concepts for students, learners and taxpayers.
The Indian Taxation Study Material 2027 series is designed as a progressive learning programme, beginning with fundamental concepts and gradually moving toward income computation, deductions, tax procedures, return filing and examination practice.
The goal is simple:
Understand the concept. Learn the rule. Practice the calculation. Apply it correctly.
26. Continue the Indian Taxation Study Material 2027 Series
You have completed:
Module 1 — Foundations of Indian Income Tax
Chapter 1 — Introduction to Indian Income Tax
Now continue with:
Chapter 2 — Important Income Tax Terminology
In the next chapter, we will build the vocabulary required to understand taxation questions, tax computations and return-filing procedures.
You will study important concepts such as:
Person → Assessee → Taxpayer → Tax Year → Assessment → Total Income → Gross Total Income → Agricultural Income → Exempt Income → Taxable Income → PAN → TDS → TCS → Return of Income
The chapter will follow the same learning architecture:
Learn → Explain → Table → Diagram → Example → Q&A → MCQs → Exam Tip → Filing Connection → Quick Check
After Chapter 2, the series will continue to:
Chapter 3 — Residential Status
Then:
Chapter 4 — Scope of Total Income
Then:
Chapter 5 — Exempt Income
Then:
Chapter 6 — Tax Rates and Tax Regimes
After completing Module 1, we will move naturally into:
Module 2 — Detailed Study of the Five Heads of Income
This progression is intentional.
First, you learn what income tax is.
Then, you learn the terminology.
Then, you learn who is taxable and to what extent.
Then, you learn what income is included or excluded.
Then, you learn how tax rates and regimes work.
Only after that do you move into detailed income computation.
That is the foundation on which the rest of the Indian Taxation Study Material 2027 series is built.
Final Learning Takeaway
If you remember only one idea from this chapter, remember this:
Income must first be understood and classified before tax can be correctly calculated.
And if you remember one sequence, remember:
Income → Classification → Taxability → Taxable Income → Tax Calculation → Tax Liability → Compliance
End of Module 1 — Chapter 1
Next: Chapter 2 — Important Income Tax Terminology
